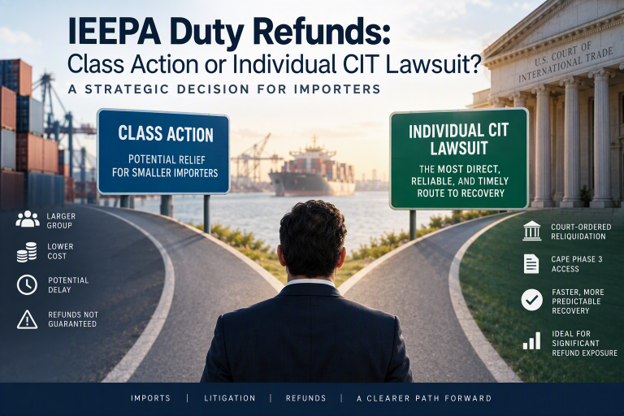
Importers seeking refunds of IEEPA duties now face an important strategic decision: join the certified class action or file an individual lawsuit in the U.S. Court of International Trade (“CIT”). While the class action may benefit smaller importers, importers with substantial refund exposure should strongly consider filing an individual CIT action. In our view, it remains the most direct, reliable, and timely route to recovery.
CBP’s CAPE Phase 3 process can now support refunds for finally liquidated entries, but only for importers that are CIT plaintiffs with qualifying court-ordered reliquidation. That makes the choice of litigation path especially consequential.
Why an Individual CIT Lawsuit Matters
To recover IEEPA duties through CAPE Phase 3, an importer generally must pursue relief in the CIT and obtain a court order directing U.S. Customs and Border Protection (“CBP”) to reliquidate the affected entries and issue the appropriate refunds. For entries that have been finally liquidated, court action is the required mechanism for obtaining relief.
Filing an individual lawsuit preserves the importer’s refund claims and creates a clear path to a court order. Once that order is obtained, the refund process generally proceeds through CBP’s CAPE Phase 3 procedures.
How the CAPE Phase 3 Refund Process Works
After an importer obtains a favorable CIT order, the typical CAPE Phase 3 process includes:
- Filing suit at the CIT.
- Obtaining a court order directing CBP to reliquidate the importer’s entries.
- Submitting a request to CBP for CAPE Phase 3 functionality, identifying the plaintiff and importer of record exactly as reflected on CBP Form 5106.
- Receiving CBP approval of the functionality request.
- Receiving an assigned filing date from CBP for the CAPE declaration.
- Submitting the CAPE declaration through ACE on the assigned date.
- CBP processing the reliquidations and Treasury issuing the refunds.
CAPE Phase 3 became available on October 6, 2026, for eligible CIT plaintiffs with court-ordered reliquidation of finally liquidated entries who received instructions from CBP to proceed with filing a CAPE 3 declaration.
The Role of the Customs Broker
Due to court-related restrictions, attorneys cannot submit CAPE declarations on behalf of importers. Instead, the importer’s customs broker will submit the CAPE declaration through ACE once Phase 3 functionality has been established.
Although the broker performs the filing, legal counsel can play an essential role throughout the process by advising on eligibility, ensuring the importer and importer-of-record information align with CBP records, and helping ensure that refund submissions are properly supported.
What the Class Action Does—and Does Not Do
The class action provides another possible recovery vehicle, but it should not be viewed as a substitute for an individual CIT action where meaningful refunds are at stake.
Class certification does not itself provide refunds, nor does it guarantee when refunds will be paid. It allows the litigation to proceed on behalf of a larger group of importers. Before any refunds can be distributed through the class action, the plaintiffs must prevail on the merits and successfully navigate any appeals.
In addition, even if the class ultimately prevails, CBP would still need to develop and implement a mechanism for processing refunds for potentially hundreds of thousands of importers. That administrative burden could add substantial delay.
Timing, Appeals, and Refund Uncertainty
We expect the government to challenge class certification and continue contesting the litigation aggressively. That may include an immediate appeal of the certification order, an appeal following any injunction, or later appellate proceedings.
As a result, refunds obtained through the class action route may not be distributed for several years—if they are distributed at all. By contrast, importers that file their own suits and obtain court orders now can proceed through the CAPE Phase 3 process that CBP recently opened for plaintiffs with qualifying court orders.
Which Option Is Best?
| Importer Situation | Recommended Approach |
| Small potential IEEPA refund | The class action may be a practical, lower-cost option. |
| Significant refund exposure | An individual CIT lawsuit is generally the strongest option. |
| Finally liquidated entries | An individual CIT action and court-ordered reliquidation are generally necessary for CAPE Phase 3 recovery. |
| Importer seeking the fastest, most predictable recovery | An individual action provides the clearest route to a court order and CAPE Phase 3 access. |
The class action may ultimately benefit smaller importers whose potential refunds do not justify the expense of individual litigation. But where the amount at issue is significant, an individual CIT action offers the quickest, strongest, and most predictable avenue for recovery. It also avoids uncertainty associated with class-action administration, appeals, and potential reductions in payout due to class-action attorney fees.
Our Recommendation
For importers with substantial IEEPA refund exposure, we believe the best course of action is to file an individual lawsuit in the CIT to secure a court order directing reliquidation of the importer’s entries and to place the importer in the existing CAPE refund process.
While the class action may eventually provide relief to class members, an individual action offers the clearest path to obtaining refunds in the shortest timeframe and minimizes the risk of delay from appeals and class-wide administration.
OFW Law is actively litigating IEEPA refund cases in the CIT on behalf of numerous clients. Please contact our Customs and International Trade team with any questions about your eligibility, refund exposure, or next steps.